The end of the earnings season is always a good time to take a step back and see who shined (and who didn’t). Let’s take a look at how medical devices & supplies - diversified stocks fared in Q2, starting with CooperCompanies (NASDAQ: COO).
The medical devices industry operates a business model that balances steady demand with significant investments in innovation and regulatory compliance. The industry benefits from recurring revenue streams tied to consumables, maintenance services, and incremental upgrades to the latest technologies. However, the capital-intensive nature of product development, coupled with lengthy regulatory pathways and the need for clinical validation, can weigh on profitability and timelines. In addition, there are constant pricing pressures from healthcare systems and insurers maximizing cost efficiency. Over the next several years, one tailwind is demographic–aging populations means rising chronic disease rates that drive greater demand for medical interventions and monitoring solutions. Advances in digital health, such as remote patient monitoring and smart devices, are also expected to unlock new demand by shortening upgrade cycles. On the other hand, the industry faces headwinds from pricing and reimbursement pressures as healthcare providers increasingly adopt value-based care models. Additionally, the integration of cybersecurity for connected devices adds further risk and complexity for device manufacturers.
The 5 medical devices & supplies - diversified stocks we track reported a satisfactory Q2. As a group, revenues beat analysts’ consensus estimates by 2.2% while next quarter’s revenue guidance was 2.2% below.
While some medical devices & supplies - diversified stocks have fared somewhat better than others, they have collectively declined. On average, share prices are down 4.1% since the latest earnings results.
Weakest Q2: CooperCompanies (NASDAQ: COO)
With a history dating back to 1958 and a portfolio spanning two distinct healthcare segments, Cooper Companies (NASDAQ: COO) develops and manufactures medical devices focused on vision care through contact lenses and women's health including fertility products and services.
CooperCompanies reported revenues of $1.07 billion, flat year on year. This print fell short of analysts’ expectations by 2.9%. Overall, it was a softer quarter for the company with a significant miss of analysts’ organic revenue estimates and a miss of analysts’ full-year EPS guidance estimates.
"This quarter included a number of notable developments including earnings exceeding expectations, record free cash flow, solid fertility growth at CooperSurgical, and a favorable completion of a significant tax matter. At CooperVision, however, we reduced U.S. channel inventory that weighed on our results and will continue to impact Q4," said Al White, President and CEO of CooperCompanies. "Following the completion of the strategic review, we are focused on profitable growth, strong cash flow generation, disciplined capital allocation, and maximizing long-term shareholder value."
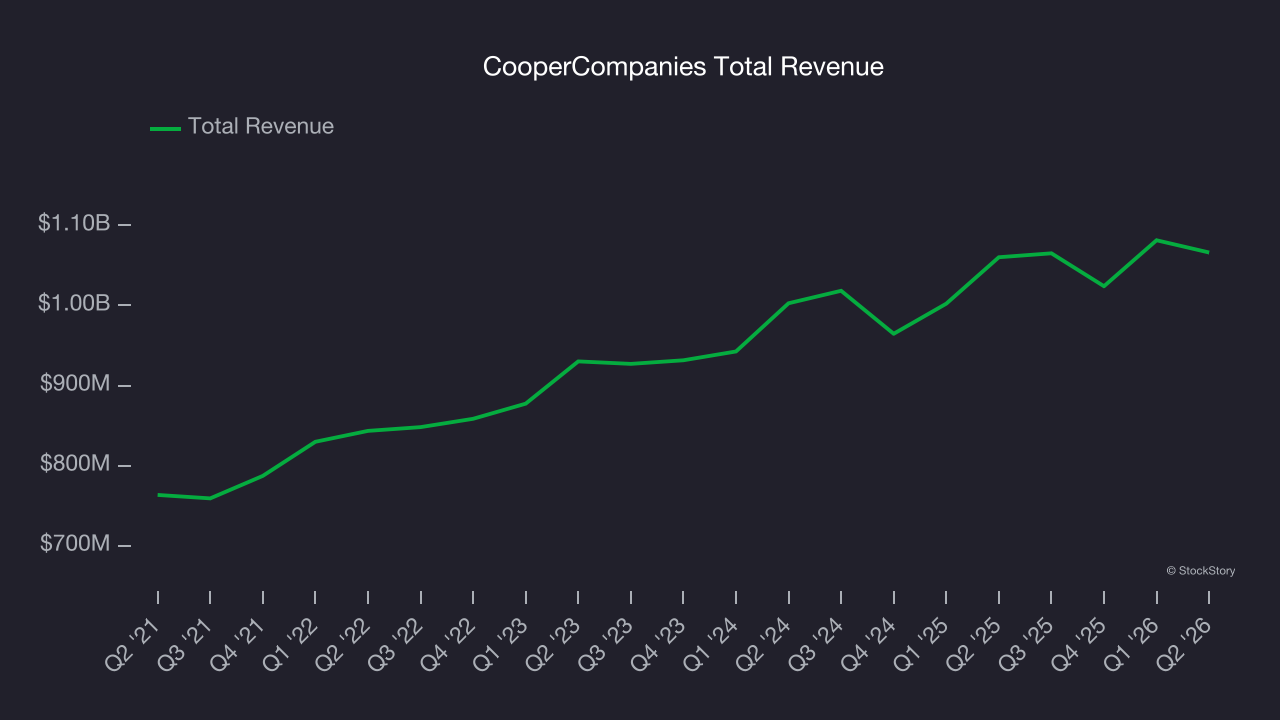
CooperCompanies delivered the weakest performance against analyst estimates, slowest revenue growth, and weakest full-year guidance update among its peers. The market seems disappointed with the results as the stock is down 14% since reporting and currently trades at $54.58.
Read our full report on CooperCompanies here, it’s free.
Best Q2: Baxter (NYSE: BAX)
With a history dating back to 1931 and products used in over 100 countries, Baxter International (NYSE: BAX) provides essential healthcare products including dialysis therapies, IV solutions, infusion systems, surgical products, and patient monitoring technologies to hospitals and clinics worldwide.
Baxter reported revenues of $2.96 billion, up 5.3% year on year, outperforming analysts’ expectations by 6%. The business had an incredible quarter with a beat of analysts’ EPS estimates and an impressive beat of analysts’ full-year EPS guidance estimates.
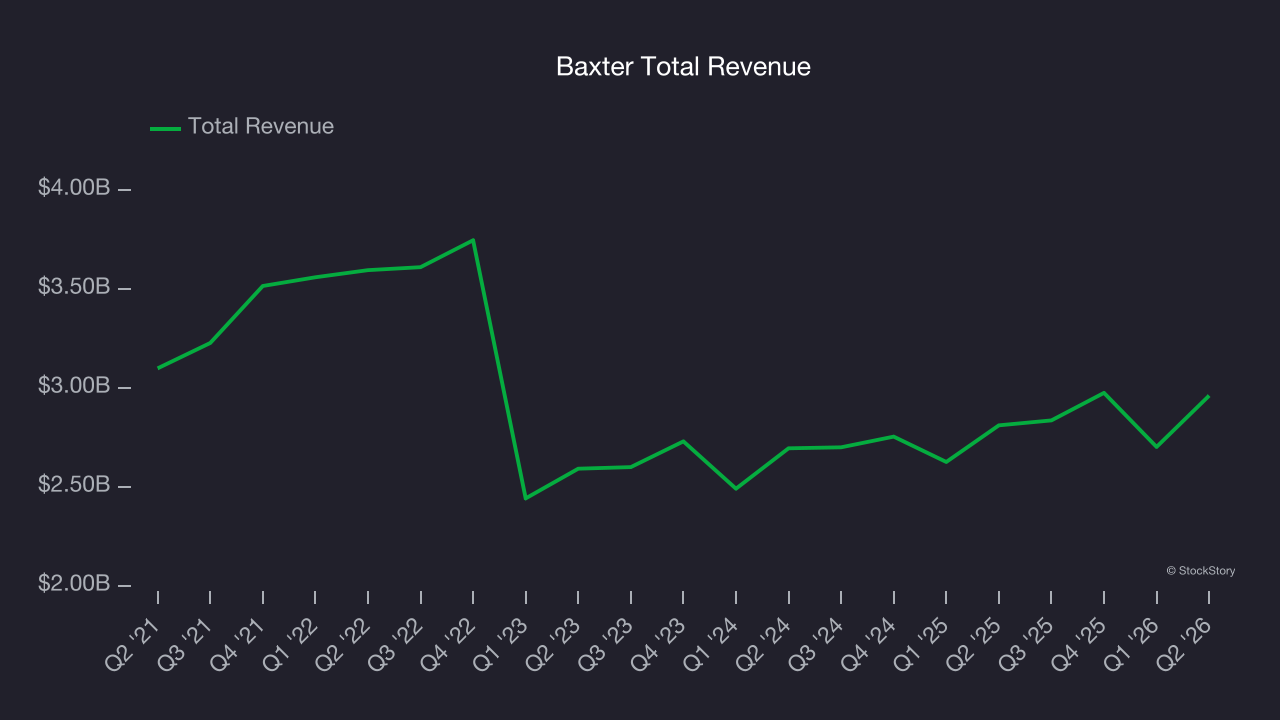
However, the results were likely priced into the stock as it’s traded sideways since reporting. Shares currently sit at $24.92.
Is now the time to buy Baxter? Access our full analysis of the earnings results here, it’s free.
Boston Scientific (NYSE: BSX)
Founded in 1979 with a mission to advance less-invasive medicine, Boston Scientific (NYSE: BSX) develops and manufactures medical devices used in minimally invasive procedures across cardiovascular, urological, neurological, and gastrointestinal specialties.
Boston Scientific reported revenues of $5.44 billion, up 7.5% year on year, exceeding analysts’ expectations by 1.5%. Still, it was a softer quarter as it posted revenue guidance for next quarter missing analysts’ expectations significantly and a miss of analysts’ full-year EPS guidance estimates.
As expected, the stock is down 6.2% since the results and currently trades at $43.23.
Read our full analysis of Boston Scientific’s results here.
Abbott Laboratories (NYSE: ABT)
With roots dating back to 1888 when founder Dr. Wallace Abbott began producing precise, dosage-form medications, Abbott Laboratories (NYSE: ABT) develops and sells a diverse range of healthcare products including medical devices, diagnostics, nutrition products, and branded generic pharmaceuticals.
Abbott Laboratories reported revenues of $12.59 billion, up 13% year on year. This result beat analysts’ expectations by 1.1%. Overall, it was a satisfactory quarter as it also produced a narrow beat of analysts’ full-year EPS guidance estimates.
Abbott Laboratories pulled off the fastest revenue growth in the group. The stock is up 15.4% since reporting and currently trades at $103.01.
Read our full, actionable report on Abbott Laboratories here, it’s free.
Neogen (NASDAQ: NEOG)
Founded in 1981 and operating at the intersection of food safety and animal health, Neogen (NASDAQ: NEOG) develops and manufactures diagnostic tests and related products to detect dangerous substances in food and pharmaceuticals for animal health.
Neogen reported revenues of $222.8 million, up 6.5% year on year. This number topped analysts’ expectations by 7%. Overall, it was a very strong quarter as it also recorded a beat of analysts’ EPS estimates and full-year revenue guidance meeting analysts’ expectations.
Neogen delivered the biggest analyst estimate beat and highest full-year guidance raise of the whole group. The stock is down 2% since reporting and currently trades at $11.73.
Read our full, actionable report on Neogen here, it’s free.
Market Update
Over the past year, investors have been forced to repeatedly answer the same question: what is the market’s biggest risk? The answer has changed several times, and each shift has reshaped market leadership.
Late in 2025 and early 2026, artificial intelligence became the market’s primary uncertainty. Investors questioned whether AI would erode software pricing power and weaken competitive moats as AI made it easier to replicate once-differentiated products.
By the spring, technology took a back seat to geopolitics. The U.S. conflict with Iran briefly became the market’s dominant narrative, raising concerns about oil prices, inflation, and global growth. But as energy markets remained orderly and fears of a prolonged supply disruption faded, investors quickly turned their focus back to fundamentals.
Want to invest in winners with rock-solid fundamentals? Check out our Hidden Gem Stocks and add them to your watchlist. These companies are poised for growth regardless of the political or macroeconomic climate.