Industrial construction and maintenance company Matrix Service (NASDAQ: MTRX) missed Wall Street’s revenue expectations in calendar Q3 2026 (fiscal Q1 2027) as revenue rose 3.5% year on year to $219.4 million. Its non-GAAP profit of $0.23 per share was 27.8% above analysts’ consensus estimates.
For more on Matrix Service, read our free full research report.
Matrix Service (MTRX) Q3 CY2026 highlights:
- Revenue $219.4 million vs S&P analysts’ consensus estimates of $239.8 million (3.5% year-on-year growth, 8.5% miss)
- Adjusted EPS $0.23 vs S&P analysts’ consensus estimates of $0.18 (27.8% beat)
- Adjusted EBITDA $7.73 million vs analysts’ consensus estimates of $7.25 million (3.5% margin, 6.5% beat)
- Operating margin 2%, up from -1% in the same quarter last year
- Free cash flow -$37.72 million compared to -$27.91 million in the same quarter last year
- Backlog $872.6 million at quarter end, down 24.8% year on year
- Market capitalization $270.5 million
“Double-digit organic revenue growth in our Storage and Terminal Solutions and Process and Industrial Facilities segments, led by specialty storage and mining and minerals activity, more than offset lower natural gas peak shaving volumes in Utility and Power Infrastructure,” continued Shawn P. Payne. “Book-to-bill was at or above 1.0x in both Utility and Power Infrastructure and Process and Industrial Facilities. First quarter awards include a limited notice to proceed for a meaningful power generation project supporting data center infrastructure, an award that combines our power generation expertise, construction-only capabilities, and growing participation in data center-related infrastructure. We also secured new mining and minerals work in the quarter, demonstrating continued commercial momentum in a market where we see favorable long-term investments trends. Also during the quarter, and as previously disclosed, we were selected to complete the front-end engineering and design of the storage tank farm for the America First Refining facility in Brownsville, Texas, which is expected to be the first major new refinery constructed in the United States in more than 50 years. These awards, together with LNG storage, substation, and mining projects already underway, demonstrate the breadth of opportunities available across our end markets. With sustained customer investment in LNG and NGL infrastructure, power generation and electrical infrastructure, data centers, and mining and minerals, we remain focused on converting our opportunity pipeline into high-quality backlog as larger pursuits reach final investment decision.
Revenue growth
Reviewing a company’s long-term revenue performance reveals insights into its quality. Any business can have short-term success, but a top-tier one grows for years. Matrix Service’s revenue grew at a tepid 6% annualized rate over the last five years, a pace that compared poorly with the rest of the industrials sector. Still, there are things to like about Matrix Service.
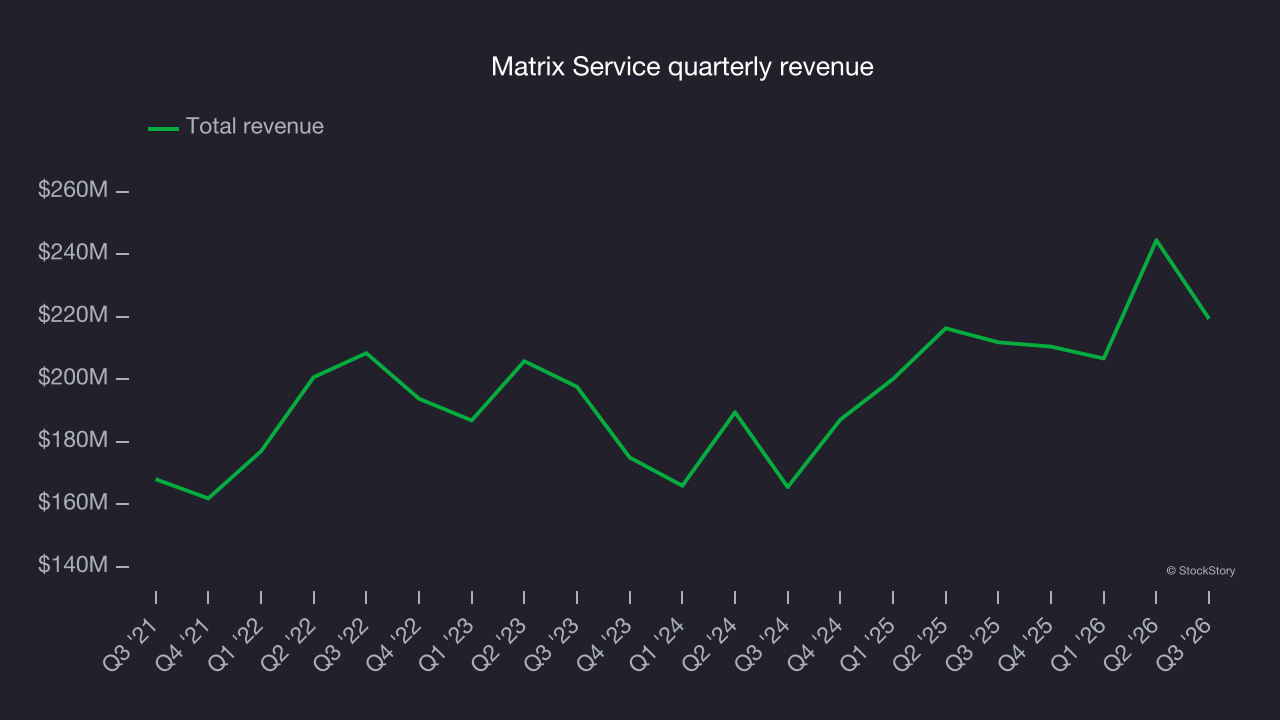
Long-term growth is the most important, but within industrials, a half-decade historical view may miss new industry trends or demand cycles. Matrix Service’s annualized revenue growth of 12.5% over the last two years is above its five-year trend, suggesting its demand recently accelerated. 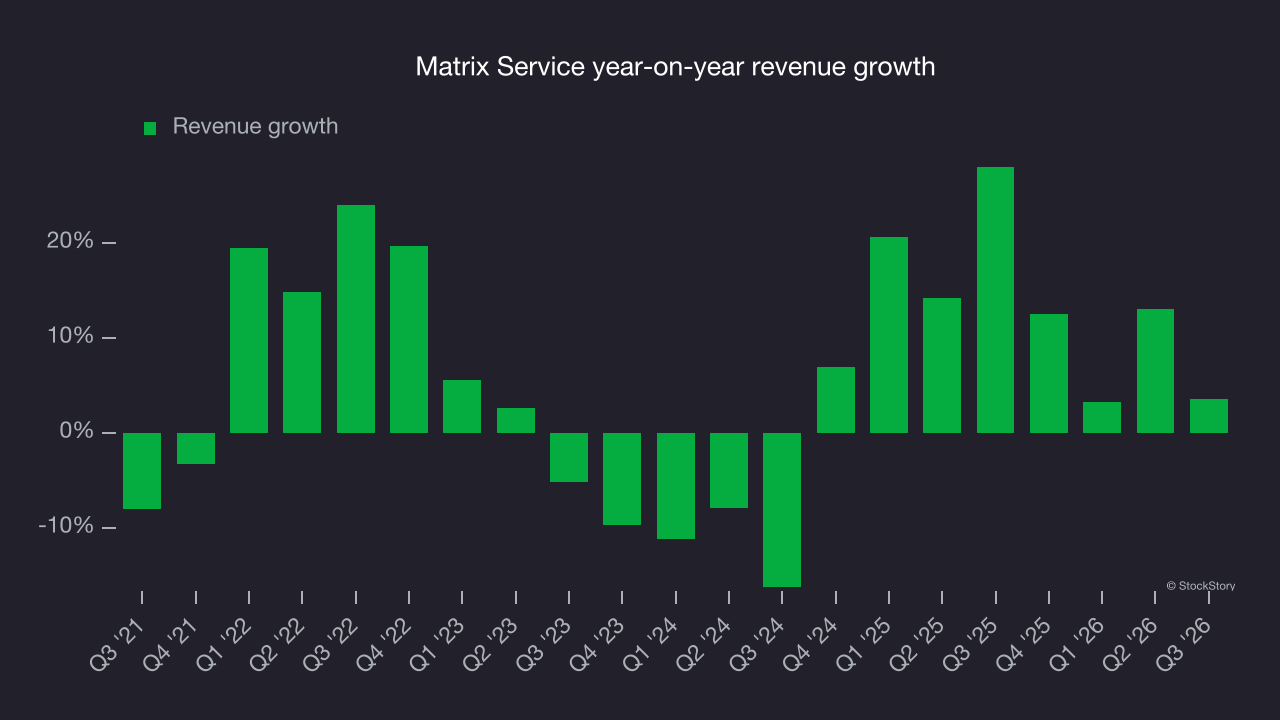
This quarter, Matrix Service’s revenue grew by 3.5% year on year to $219.4 million, falling short of Wall Street’s consensus estimates.
Looking ahead, sell-side analysts expect revenue to grow 4.6% over the next 12 months, according to S&P, a deceleration versus the last two years. This projection is underwhelming and indicates its products and services will face some demand challenges. Still, the company is performing well on other measures of financial health.
Operating margin
Operating margin is one of the best measures of profitability because it shows how much money a company keeps after procuring and manufacturing its products, marketing and selling those products and, most importantly, keeping them relevant through research and development.
Although Matrix Service was profitable this quarter on an operating basis, it has generally struggled over a longer period. Its expensive cost structure has contributed to an average operating margin of negative 3.6% over the last five years. Unprofitable industrials companies require extra attention because they can be vulnerable when business conditions deteriorate.
On the positive side, Matrix Service’s operating margin rose by 7.8 percentage points over the last five years, as its revenue growth gave it operating leverage. Still, it will take much more for the company to show consistent profitability.
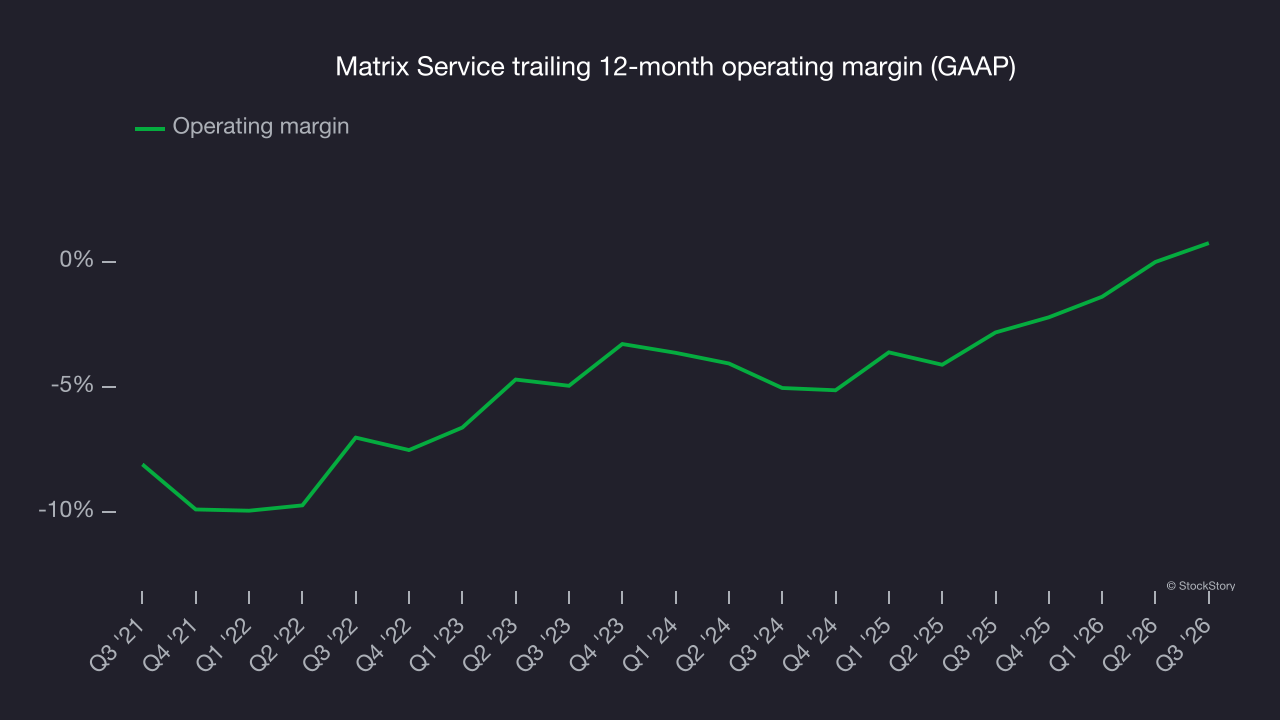
This quarter, Matrix Service generated an operating margin of 2%, up 3.1 percentage points year on year. The increase was a positive sign, and operating margin rising more than gross margin suggests it was more efficient with expenses such as marketing, research and development and administrative overhead.
Earnings per share
Long-term changes in earnings per share, or EPS, matter for the same reason as long-term revenue growth. Compared to revenue, however, EPS highlights whether a company’s growth is profitable.
Matrix Service’s full-year EPS flipped from negative to positive over the last five years. This is a good sign and shows it’s at an inflection point.
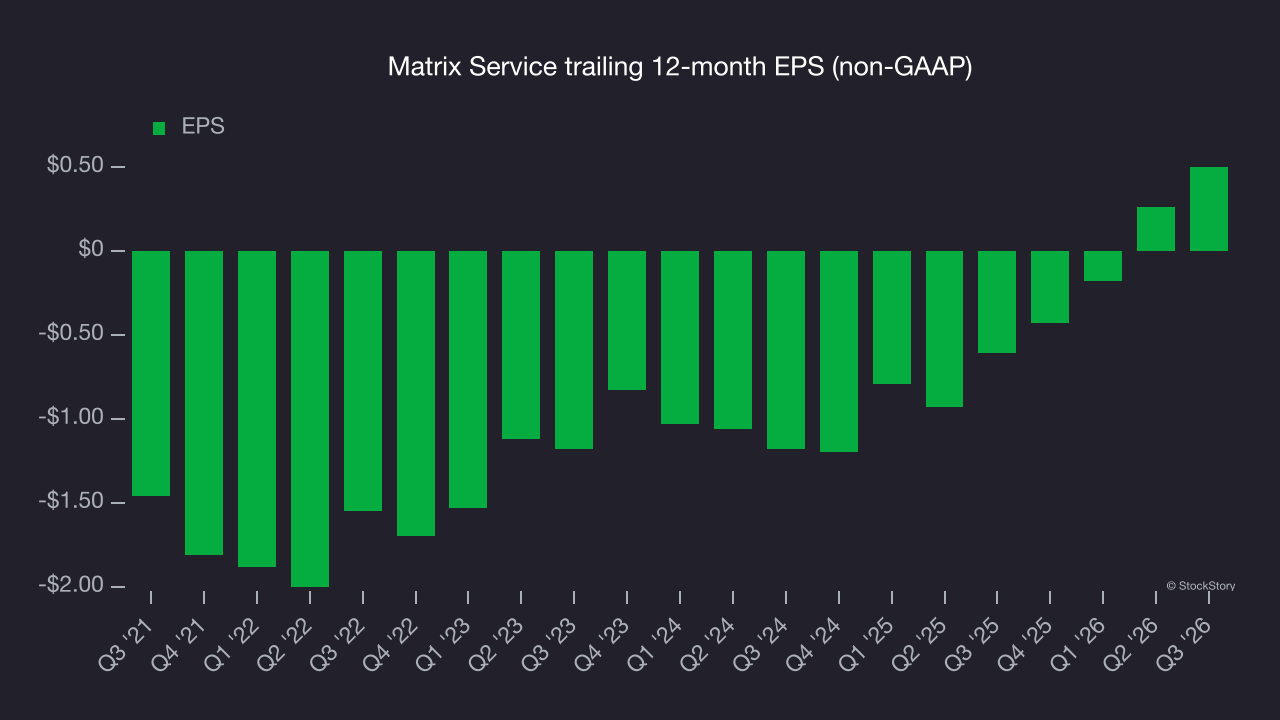
As with revenue, EPS over a more recent period can provide insight into an emerging theme or development for the business.
For Matrix Service, its two-year annual EPS growth of 55.7% was higher than its five-year trend. That acceleration is a positive sign, particularly given the already high base.
In Q3, Matrix Service reported adjusted EPS of $0.23, up from negative $0.01 in the same quarter last year. The result comfortably beat analysts’ consensus estimates, a positive outcome for shareholders. Over the next 12 months, Wall Street expects Matrix Service’s full-year EPS to grow 21% from $0.50 to $0.61, according to S&P.
Key takeaways from Matrix Service’s Q3 results
Matrix Service’s quarter had some key positives: EPS beat analysts’ consensus estimates and EBITDA topped Wall Street’s consensus. Revenue, however, missed expectations. Shares surged 9.1% to $9.99 immediately after the results.
Matrix Service had a solid quarterly earnings result, but is the stock a good investment? The latest quarter does matter, but not nearly as much as longer-term fundamentals and valuation when deciding if the stock is a buy. For more on those factors, read our full research report here (it’s free).